Many beginners think that growing rich takes lucky market timing, fast trades, and reckless bets. But the real path to financial freedom is much calmer and far more reliable. The charlie munger rules of wealth show that patient compounding, dodging big blunders, and staying inside what you know will build lasting prosperity over time.
Charlie Munger proved that quiet discipline beats clever shortcuts in every market cycle. By avoiding deadly portfolio drops and letting quality holdings grow undisturbed, you can build serious wealth without guessing what stocks will do next week.
Key Takeaways
- Getting rich slowly shields you from reckless moves that wipe out hard-earned cash.
- Losses hurt far more than gains help because portfolio recovery math is steep.
- Taxes and fees quietly erase more than half of your potential long-term returns.
- Buying great businesses with durable moats beats chasing cheap, struggling operations.
- Holding ample cash reserves gives you peace of mind and dry powder for bargains.
- Knowing your personal limits stops you from playing games where others hold an edge.
- Dumping your own flawed ideas protects your capital as conditions change.
What Are the Core Tenets of Charlie Munger’s Wealth Philosophy?
Charlie Munger’s wealth philosophy rests on a simple truth: grow your money steadily by avoiding foolish choices and letting compound interest work without stop.
Think of your personal finances like building a stone house. If you build on loose sand to finish fast, a single heavy storm washes it away. But when you anchor the walls deep into solid rock, the house stands firm for decades. Munger treated his wealth the same way, choosing safety and patience over quick thrills.
Many investors fail because they chase exciting trends that they do not understand. In contrast, Munger chose to focus on basic arithmetic and steady habits. He knew that simple rules, followed year after year, lead to remarkable results. So, he built a life around clear thinking and patient waiting.
Because he did not care about showing off, he never felt rushed to keep up with the crowd. He knew that the market tests your emotions constantly. If you can control your impulses when others panic, you will come out ahead. Thus, his core philosophy is as much about emotional control as it is about finance.
From Omaha to Berkshire Hathaway
Charlie Munger was born on January 1, 1924, in Omaha, Nebraska. He built a legendary career rooted in plain speech, deep reading, and clear logic. In fact, Charlie Munger and Warren Buffett first met in Omaha, Nebraska, in 1959 at a dinner arranged by mutual friends. That dinner sparked a famous partnership that reshaped modern investing.
Before working full-time with Buffett, Munger ran his own successful investment firm. Later on, he formally became vice chairman of Berkshire Hathaway in 1978. He served in that role with distinction for decades. Sadly, he passed away on November 28, 2023, at 99 years of age, just weeks short of his 100th birthday. Over his long life, Munger showed that sound judgment and patience win the long game.
Buffett and Munger worked as a team, yet each brought distinct strengths to the table. Buffett loved finding statistical bargains, while Munger pushed for business quality. Together, they turned a failing textile mill into a massive global powerhouse. But through it all, Munger stayed humble and kept his lifestyle remarkably grounded.
He often gave credit to good habits rather than raw genius. For instance, he read constantly and reflected on human nature every day. Because he studied how people make bad choices, he could spot traps before falling into them. That rare habit saved Berkshire Hathaway from countless Wall Street manias.
The Power of the ‘Get Rich Slow’ Formula
Wall Street often tempts beginners with promises of quick profits. Yet Munger viewed that frantic mindset as a toxic trap for everyday families. When you hurry to get rich, you take foolish risks that endanger your security.
True compounding requires emotional calm rather than constant trading. If you buy great assets and leave them alone, time does the heavy lifting for you. Munger explained his calm approach to wealth creation in very clear words:
“I don’t have any advice for young people who want to get rich. Basically, I think the desire to get rich fast is pretty dangerous. My own system was to get rich slow”— Charlie Munger, Vice Chairman of Berkshire Hathaway, The Economic Times
Because slow wealth relies on steady math, it does not depend on market luck. You do not need to read stock charts all day. Instead, you can live your life while your money compounds in the background. That peace of mind is the greatest benefit of all.
Furthermore, trying to rush returns often pushes investors toward risky margin loans and penny stocks. These tools promise huge upside, but they expose you to total ruin. When you accept a slower pace, you eliminate the threat of sudden bankruptcy. That simple shift changes your whole financial life for the better.
So, the real secret of the wealthy is not a hidden trading trick. It is simply the ability to sit still when everyone else is running around. If you give compounding enough room, even modest savings grow into serious wealth.
Why Is Avoiding Catastrophic Loss the Primary Rule of Compounding?
Avoiding severe losses is the first rule of compounding because math works against you whenever your portfolio takes a heavy hit.
Many new investors assume that gains and losses balance out evenly. For example, people often believe that a loss is easily fixed by an equal gain. But portfolio math does not work that way at all. When you lose money, your base shrinks, so future gains must work much harder.
This mathematical truth is why Munger spent so much time studying failure. He wanted to know where businesses run into trouble so he could steer clear. In personal finance, protecting what you already have is always job number one. If you protect your downside, the upside will take care of itself.
In addition, big losses take an emotional toll that numbers cannot capture. When people see their savings collapse, they tend to panic and sell at the exact bottom. That locks in temporary drops as permanent damage. Thus, avoiding huge drops protects both your bank account and your peace of mind.
The Brutal Mathematics of Drawdowns
When an account suffers a severe drawdown, the climb back to even is grueling. For example, a portfolio that experiences a 50% loss requires a 100% gain simply to return to its original break-even point. If your capital drops by half, you must double your money just to get back to square one.
The math gets far worse during extreme crashes. In fact, a severe market drop of 75% requires an investor to achieve a 300% gain just to recover initial principal. Because producing a 300% return can take decades, a single bad crash can ruin your retirement plans forever.
That is why reckless bets are so harmful. If you lose most of your money on a hot tip, you may never catch up. Compounding needs continuity to work its magic. When you cut your principal down to a fraction, the compounding chain breaks completely.
Consider how difficult it is to earn double or triple your money in normal markets. Even great index funds take years to achieve those numbers. Therefore, protecting your capital from deep drops must always be your top priority as an investor.
Portfolio Drawdown and Required Recovery Gain
| Portfolio Drawdown | Required Gain to Break Even |
|---|---|
| 50% Loss | 100% Gain |
| 75% Loss | 300% Gain |
Being Consistently Not Stupid
Because recovery math is so steep, Munger focused on avoiding dumb mistakes. He did not chase wild tech fads or complex financial schemes. Instead, he worked to eliminate basic errors, unvetted debt, and rash choices.
Dodging clear mistakes creates far better long-term returns than trying to be a genius. Munger highlighted this practical truth in a famous quote:
“It is remarkable how much long-term advantage people like us have gotten by trying to be consistently not stupid, instead of trying to be very intelligent.”— Charlie Munger, Vice Chairman of Berkshire Hathaway, New Trader U
Most investors stumble because they try too hard to outsmart everyone else. They trade too often, jump between funds, and take on heavy debt. But Munger showed that basic common sense is rare and valuable. If you simply stay out of your own way, you beat most participants.
This means you do not need an advanced finance degree to succeed. You just need the discipline to say no to dubious ideas. When someone pitches a shortcut with huge returns, remember Munger’s rule. Walking away from foolish bets keeps your wealth intact.
Warning: Debt and Speculation Can Wipe You Out
Borrowing money to buy stocks exposes you to catastrophic losses. When prices slide, lenders can force you to sell your shares at fire-sale lows. Because a 50% drop takes a 100% gain just to recover, taking on debt turns normal market swings into permanent financial ruin.
How Do Taxes and Management Fees Silently Destroy Wealth?
Taxes and advisory fees silently destroy wealth by taking a bite out of your money before it has the time to compound.
Picture your investments as a rolling snowball on a snowy hill. Every time you roll it forward, it picks up more snow. But if someone scrapes off a layer of snow every few feet, the snowball stays tiny. That constant scraping is what annual fees and trading taxes do to your portfolio.
Many investors ignore small fees because a couple of percentage points sound harmless. However, that cost compounds against you every single year. Over decades, that slow leak drains away most of the money you could have enjoyed in retirement.
Because costs happen quietly in the background, you rarely notice the damage in the short run. Your statement might still show small gains, so you feel content. But when you look at the total wealth lost over 30 years, the outcome is shocking. Minimizing these costs is one of the easiest ways to keep more money.
The 30-Year Friction Drag Illustrated
To see how friction hurts your future, look at real numbers over three decades. For example, a starting sum of $10,000 compounding undisturbed at 10% annually over 30 years grows to approximately $174,494. That huge gain happens because every dollar stays invested and works for you.
Now look at what happens when friction takes its cut. When taxes and management fees absorb 30% of annual gains to reduce a 10% gross return to 7%, a $10,000 portfolio reaches only about $76,123 after 30 years, forfeiting 56% of potential terminal wealth. You lose more than half your potential nest egg without making a single bad stock pick.
That missing money is not just the fees themselves. It is the future compound growth that those lost dollars would have produced. When a dollar leaves your account, you lose all the work it would have done for the next twenty years. That is why friction is so lethal to your net worth.
So, keeping your costs low is not just about saving pennies today. It is about protecting the huge tree that those pennies could have grown into. Every fee you eliminate stays in your pocket and compounds for your family.
Worked Example: The Cost of Compounding Interruption
Starting Investment: $10,000
Timeline: 30 years
Gross Growth Rate: 10% annually
- Undisturbed Compounding at 10%: Grows to approximately $174,494.
- Compounding with 30% Tax and Fee Drag (7% Net): Reaches only about $76,123.
- Wealth Forfeited: You forfeit 56% of your potential terminal wealth to friction.
Small annual costs snowball into massive losses over a long investing lifetime.
Minimizing Interruption in Your Compounding Machine
The greatest danger to long-term wealth is interrupting compound interest without good reason. When you sell shares frequently, you trigger taxes that leave your account for good. In addition, high management fees drag down your base return year after year.
Because Munger understood this math, he favored buying outstanding businesses and holding them for decades. He did not jump in and out of the market to catch quick moves. In fact, he summed up his whole trading strategy in one short sentence:
“The big money is not in the buying and selling, but in the waiting.”— Charlie Munger, Vice Chairman of Berkshire Hathaway, New Trader U
Active trading gives you the illusion of progress, but it usually generates lower returns and higher tax bills. By trading less, you keep your expenses down and let compound interest do its job. Sitting quietly is often the most profitable move an investor can make.
Therefore, look closely at what you own and how much you pay to hold it. High expense ratios and frequent turnover are enemies of wealth. If you switch to low-cost, patient strategies, your future self will thank you.
Impact of 30% Fee and Tax Drag on a $10,000 Portfolio Over 30 Years
| Compounding Scenario | Annual Net Growth Rate | Final Portfolio Value (30 Years) | Loss of Terminal Wealth |
|---|---|---|---|
| Undisturbed Compounding | 10% | $174,494 | Base Result |
| Compounding with Fee and Tax Friction | 7% | $76,123 | 56% |
Why Was See’s Candies the Definitive Turning Point in Munger’s Strategy?
See’s Candies was the turning point in Berkshire Hathaway’s strategy because it showed Munger and Buffett that buying a great business at a fair price beats buying cheap, struggling firms.
Early on, Warren Buffett focused on classic value investing. He looked for dying businesses selling at deep discounts to their liquidation value. But Charlie Munger realized that a mediocre company is a poor investment, no matter how cheap it looks. Instead, he argued that firms with loyal customers and real pricing power generate far better wealth over time.
This insight marked a major shift in how Berkshire invested its money. It moved the company away from struggling operations and toward high-grade businesses. That single philosophy change paved the way for Berkshire’s greatest long-term successes.
For everyday investors, this lesson is just as important. A cheap stock is often cheap for a very good reason. If a business loses money or faces fierce competition, low share prices will not save you. Quality matters far more than a cheap price tag.
Moving Beyond Bargain Hunting
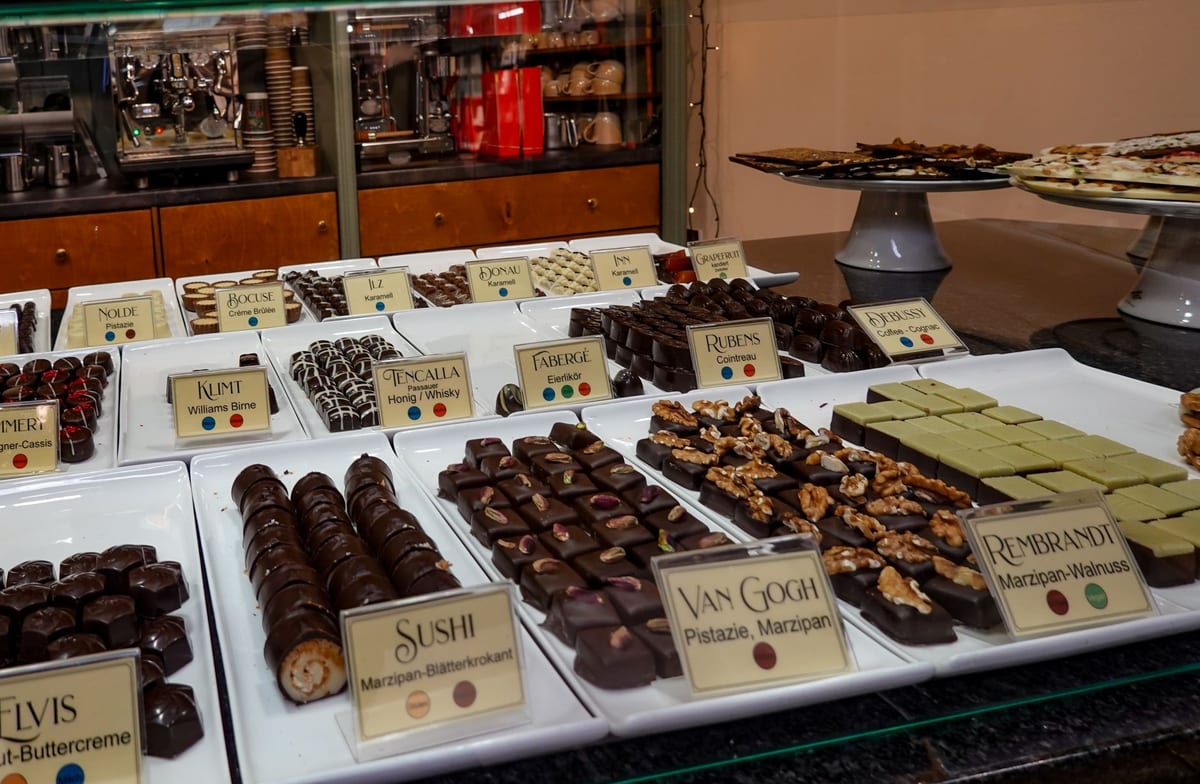
Berkshire Hathaway bought See’s Candies in 1972 for $25 million at Charlie Munger’s urging. At the time, paying that price for a boxed chocolate maker surprised many value purists. They thought Buffett and Munger were paying far too much for ordinary candy stores.
However, See’s held a huge asset that balance sheets could not show: a powerful brand moat. People loved the chocolates and happily paid higher prices every year without switching to rival brands. As a result, See’s generated steady profits without needing expensive new factories or heavy machinery.
This meant See’s could raise its prices without losing sales. That pricing power protected the business against inflation and competition. When input costs went up, See’s simply raised its box prices, and loyal buyers kept lining up.
Because the business required very little capital to run, almost all its earnings could be sent back to Berkshire. That surplus cash was then used to buy other great businesses. See’s became an engine that powered Berkshire’s future growth.
The $2 Billion Lesson in Economic Moats
The long-term payoff from that purchase was massive. In fact, See’s Candies has generated cumulative pre-tax earnings of over $2 billion for Berkshire Hathaway on its initial purchase price. That tiny candy maker sent a flood of cash back to headquarters for decades.
A durable competitive advantage lets a company raise prices while keeping rivals at bay. By steering Berkshire away from fair companies at cheap prices toward wonderful companies at fair prices, Munger altered the firm’s destiny forever.
That $2 billion cash stream was put to work buying blue-chip stocks and rail networks. Without the lessons learned from See’s, Berkshire would never have made its biggest, most profitable investments. Munger’s insistence on business quality made all the difference.
When you invest, look for companies that share those same qualities. Seek businesses with devoted customers, low reinvestment needs, and strong brands. These firms compound capital year after year, protecting you from market storms.
What this means for you
Do not buy a stock just because its price fell off a cliff. A troubled company can keep falling until it goes broke. Instead, look for solid firms with loyal buyers, low overhead, and pricing power. Paying a reasonable price for a wonderful company will protect your savings far better over time.
What Does Charlie Munger’s Alibaba Trade Teach Us About Risk?
Charlie Munger’s Alibaba investment shows that even top investors can make missteps when they fall in love with an exciting story.
No one gets every call right, and Munger was famous for his honesty when things went wrong. Later in life, he stepped outside his normal habits to take a large position in Chinese e-commerce. Looking at what happened gives beginners a masterclass in humility and risk control.
It also shows why having a clear plan for mistakes is essential. Many people let bad investments fester because they cannot admit they were wrong. But Munger knew that protecting capital requires cutting losses when the facts change. He did not let pride get in the way of sound logic.
So, studying Munger’s rare mistakes is just as useful as studying his wins. It proves that discipline is not about being flawless. Rather, it is about keeping mistakes small and learning from them quickly.
The Accumulation and Downsizing of Daily Journal’s Stake
Munger served as chairman of Daily Journal Corporation until stepping down from the leadership chair in 2022 while remaining on the board. Under his guidance, Daily Journal purchased 165,300 American depositary shares of Alibaba in the first quarter of 2021 for roughly $37.5 million.
When the stock price dropped, Munger added to the holding. By the close of 2021, Daily Journal’s position in Alibaba expanded to approximately 602,000 shares worth $72 million, making up roughly 28% of its total equity portfolio. But fierce retail competition and regulatory shifts altered the business reality. Facing these new facts, Daily Journal Corporation reduced its Alibaba stake by half in the first quarter of 2022, selling 302,060 shares to leave a remaining balance of 300,000 shares.
Selling that large block meant admitting that the original thesis had holes. Yet Munger did not hesitate to act when the numbers no longer made sense. He knew that holding onto a bad idea out of stubbornness only makes things worse.
That quick pivot protected the company from deeper losses down the road. It showed that even at an advanced age, Munger was willing to adjust his positions based on new evidence. That flexibility is a vital trait for every investor.
Daily Journal Corporation Alibaba Position Changes (2021–2022)
| Timeline | Alibaba Share Count | Estimated Position Value | Portfolio Context |
|---|---|---|---|
| Q1 2021 Purchase | 165,300 shares | Roughly $37.5 million | Initial entry into Chinese tech |
| Close of 2021 Peak | Approximately 602,000 shares | $72 million | Roughly 28% of total equity portfolio |
| Q1 2022 Reduction | 300,000 shares remaining | Reduced by half | Sold 302,060 shares after reassessing |
Destroying Best-Loved Ideas When Facts Change
What made Munger special was his total lack of ego about his blunders. He did not blame market makers or bad luck. Instead, he owned his mistake with complete clarity:
“I regard Alibaba as one of the worst mistakes I ever made. In thinking about Alibaba, I got charmed with the idea of their position on the Chinese internet. I didn’t stop to realize they’re still a goddamn retailer. It’s going to be a competitive business, the internet. It’s not going to be a cakewalk for everybody.”
— Charlie Munger
When the facts change, your investment thesis must change right along with them. Munger practiced what he preached, urging investors to challenge their own fondest beliefs:
“Any year that you don’t destroy one of your best-loved ideas is probably a wasted year”
— Charlie Munger
Most investors cling to losers because selling feels like admitting defeat. But real success comes from facing reality head-on. If the reasons you bought a stock turn out to be wrong, taking your medicine and moving on is the smart choice.
So, do not let your feelings tie you to a sinking ship. When you realize you made a bad call, step back and re-evaluate. That emotional honesty will save you more money than any fancy trading system.
Why Does Berkshire Hathaway Hold Massive Cash and Treasury Reserves?
Berkshire Hathaway keeps giant cash and short-term Treasury reserves because liquidity guarantees survival during panics and provides buying power when bargains appear.
Many everyday investors feel uneasy keeping cash on the sidelines. They worry that inflation will slowly erode their buying power, so they rush to invest every dollar right away. However, Munger and Buffett viewed cash as vital insurance against market chaos.
Having cash gives you the power to think clearly when other people are panicking. If you are fully invested or deep in debt, a market crash threatens your survival. But if you have cash on hand, a market crash looks like an opportunity.
In addition, holding cash means you never have to sell good assets at bad prices. If you need cash for an emergency, you do not have to liquidate stocks during a downturn. That cushion protects your long-term plan from unexpected life events.
Treasury Reserves as Strategic Protection
By keeping a fortress balance sheet, Berkshire ensured it would never face bankruptcy. As of mid-2026, Berkshire Hathaway’s cash and short-term Treasury bill reserves expanded past $365 billion. That ocean of liquid cash means the company never needs bank loans or government bailouts during panics.
Holding ample cash brings peace of mind during wild market drops. While unprepared investors scramble to meet margin calls, a cash-rich investor can stay calm and search for rare bargains.
That cash hoard is not wasted money. In fact, it provides Berkshire with unparalleled strength in negotiations. When distressed companies need cash fast, they call Berkshire because they know the funds are ready right away. That allows Berkshire to extract very favorable terms.
For an individual investor, an emergency fund serves that exact same purpose. When you have several months of cash in the bank, you never panic over a job loss or a temporary market dip. You stay in control of your financial life.
By the Numbers: Berkshire Hathaway’s Cash Fortress
- $365+ Billion: Cash and short-term Treasury bill reserves held by mid-2026.
- 100%: Recovery gain needed after a 50% market drop just to break even.
- $2 Billion: Cumulative pre-tax earnings produced by See’s Candies on a $25 million initial price.
The Discipline of Waiting for Mispriced Odds
Munger compared investing to a baseball hitter waiting at the plate. In sports, you get called out if you let good pitches pass by. But in investing, there are no called strikes. You can watch dozens of overpriced stocks drift past without any penalty.
You do not have to swing at every stock that crosses your screen. You can wait months or years until an incredible opportunity arrives. Holding cash gives you the rare gift of patience while others exhaust themselves trading back and forth.
Most investors feel pressured to act every single day. They read the news and feel like they must buy or sell something. But constant motion is the enemy of good returns. Sitting still and waiting for the right pitch is much more profitable.
So, treat your cash reserves as dry powder, not idle money. When the market is expensive, doing nothing is a valid decision. Patience is a powerful tool when paired with the discipline to strike when odds are in your favor.
How Can Everyday Investors Define Their Circle of Competence?
Everyday investors can define their circle of competence by finding what they truly understand and avoiding areas where they lack clear insight.
Your circle of competence is not about how big it is. Instead, it is about how honestly you draw its borders. If you know retail or local housing, focus there. Stepping outside what you know to buy complex biotech or foreign tech firms invites serious trouble.
Many investors get into trouble because they think they must understand every hot sector. When artificial intelligence or crypto makes headlines, they rush to buy without knowing how the technology works. That behavior is a recipe for quick losses.
In contrast, Munger was happy to say “I do not understand it” and move on. He did not care if others made money on trends he avoided. He only cared about staying where he held a clear edge. That discipline kept him safe for a century.
Multidisciplinary Lessons from Caltech to Law
Charlie Munger built his wide perspective through diverse studies and career moves. For instance, Charlie Munger left the University of Michigan in 1943 to join the U.S. Army Air Corps during World War II, later studying meteorology at Caltech. After military duty, Munger was admitted to Harvard Law School without finishing an undergraduate degree, graduating magna cum laude in 1948.
After practicing law, Munger ran the investment counseling partnership Wheeler, Munger & Co. from 1962 to 1975 before fully uniting his efforts with Berkshire Hathaway. He also chaired Wesco Financial Corporation for 27 years, serving from 1984 until Berkshire acquired the remainder of the company in 2011. Through those varied roles, Munger blended ideas from physics, law, psychology, and engineering to evaluate businesses with rare clarity.
Yet life tested his emotional strength along the way. In particular, Munger experienced the loss of his first son, Teddy, who died of leukemia in 1955 at the age of nine. Through deep personal sorrow and career shifts, Munger showed that stoic grit and emotional control are the true foundation of sound decision-making.
He did not let grief make him bitter or reckless. Instead, he threw himself into constructive work and constant learning. He believed that developing good character was an investor’s first duty. That inner strength carried him through market crashes that ruined other men.
The Enduring Wisdom of Poor Charlie’s Almanack
Munger shared his mental models and down-to-earth advice in many famous speeches. The book ‘Poor Charlie’s Almanack: The Wit and Wisdom of Charles T. Munger’, edited by Peter D. Kaufman, was first published in 2005. That book remains an essential guide for anyone who wants to sharpen their thinking and master the rules of wealth.
Staying inside your circle of competence shields you from competing against pros who know far more than you do. Munger gave direct advice about playing only games where you have a genuine edge:
“You have to figure out what your own aptitudes are. If you play games where other people have the aptitudes, and you don’t, you’re going to lose.”
— Charlie Munger
When you stay within your zone of comfort, you avoid making unforced errors. You do not need to know everything about every industry. You only need to know a few good businesses better than the crowd. That focused approach gives you a massive advantage.
So, do not be afraid to admit what you do not know. Humility is your greatest financial safeguard. If an idea feels too complicated, toss it into the “too hard” pile and look for something simpler.
What this means for you
List the products and businesses you know well from your daily job or routine shopping. Stick strictly to those areas when investing your savings. If an idea falls outside that familiar boundary, pass without regret. Saying “I don’t understand this” is not a flaw; it is your best shield against disaster.
Frequently Asked Questions
What were Charlie Munger’s core rules for building long-term wealth?
Charlie Munger focused on compounding capital slowly while dodging obvious mistakes and major losses. He advised buying wonderful businesses with durable economic moats, keeping taxes and fees low, and staying inside what you know. He also kept ample cash on hand so he could buy assets when great opportunities appeared.
Why did Charlie Munger warn against trying to get rich quick?
Munger warned that rushing to get rich pushes investors toward reckless risks and excessive debt. When you hurry, you make careless choices that invite big portfolio losses. Because a 50% loss requires a 100% gain just to break even, aggressive shortcuts often destroy wealth instead of creating it.
How do management fees and taxes destroy compounding returns over 30 years?
Taxes and advisory fees chip away at your base capital every year. For example, a $10,000 portfolio compounding at 10% reaches about $174,494 after 30 years. But when fees and taxes cut that return to 7%, the final value drops to $76,123, forfeiting 56% of your potential terminal wealth.
Why was See’s Candies considered a crucial turning point in Berkshire Hathaway’s strategy?
Berkshire bought See’s Candies in 1972 for $25 million after Munger urged Buffett to look beyond cheap, troubled firms. See’s held strong brand loyalty and pricing power, generating over $2 billion in pre-tax earnings. This success convinced Berkshire to focus on wonderful businesses at fair prices.
Why did Charlie Munger call his investment in Alibaba one of his worst mistakes?
Daily Journal held an Alibaba stake worth $72 million by late 2021 before cutting it in half in early 2022. Munger admitted he got charmed by their internet position while forgetting they were still a retailer facing brutal competition. He recognized his error and reduced the position.
How does avoiding large portfolio losses help an everyday investor?
Avoiding big drops protects you from the harsh math of recovery. If you lose 50%, you need a 100% gain just to break even, and a 75% drop requires a 300% gain. Keeping your downside protected ensures that your money keeps compounding forward without suffering catastrophic setbacks.
Conclusion: Building Enduring Wealth Through Patience and Discipline
Charlie Munger proved over a life of 99 years that true wealth creation does not require frantic trading or complex schemes. Instead, mastering the charlie munger rules of wealth comes down to basic habits: avoid catastrophic losses, keep fees and taxes low, stick to what you know, and let compound growth run undisturbed for decades.
Your next step is simple. Review your current portfolio today. Check if high fees are eating your returns, confirm you are not carrying dangerous debt, and eliminate holdings outside your circle of competence. By removing unforced errors and practicing patient waiting, you give your savings the room they need to grow into lasting prosperity.